Will my money last?
Surveys now find that most people fear running out of money more than they fear dying. Longer lives and decades without a paycheck make the question of how much is enough harder than any calculator suggests.
Custom financial planning built around your goals
Sean Conrad helps YOU PROTECT what YOU built, turn it into DEPENDABLE INCOME, and pass it on as you intend.
Families served
Since 2011, across Florida and 14 other states.
Assets under management
Held at independent third-party custodians.
Client retention
Households retained year over year, five-year average.
The concerns we hear most
Most people near retirement are not chasing a bigger number. They are trying to protect the one they already have.
Surveys now find that most people fear running out of money more than they fear dying. Longer lives and decades without a paycheck make the question of how much is enough harder than any calculator suggests.
A downturn in your first years of retirement does lasting damage. The same loss hurts far more while you are withdrawing than it did while you were still saving.
For decades you were paid every two weeks. Now you have to build your own income from accounts that were never designed to hand you a steady, tax-smart check for thirty years.
A single extended illness can quietly erase decades of saving, and Medicare covers far less of it than most people assume.
Sixty-two, full retirement age, or seventy? A married couple can face dozens of claiming combinations, and the lifetime difference can reach six figures.
Taxes, probate, unclear wishes, and heirs left with a surprise bill. You want to pass on what is left cleanly and on your terms.
By the time you are within a decade of retirement, the math changes. You have less time to recover from a loss and far more to lose. So the priority shifts from building the pile to protecting it and turning it into income you can count on.
We do not chase the hottest returns or sell you a headline. We build a plan meant to hold up in bad years, generate dependable income, and keep more of what is yours away from unnecessary taxes. Steady beats spectacular when it is the money you are going to live on.
Your earning years
Accumulate
Time is on your side. A dip is a chance to buy in and recover.
Grow the pile
Make it as large as you can before you stop working.
Your retirement years
Preserve
Time is finite. A dip while you withdraw can be permanent.
Make it last
Turn it into income that will not run out, however long you live.
49%70%
Just under half of people approaching retirement feel confident building an income plan on their own. Among those working with a financial professional, it is seven in ten.
Source: Alliance for Lifetime Income, 2025 Protected Retirement Income & Planning study.
The Runway Test™
Five questions, two minutes. You get a green, amber, or red light on the rate you would need to draw, and a straight explanation of what it means.
One team, one plan
Most people stitch together an advisor, an accountant, an insurance agent, and an attorney who never speak to each other. Sean built Penfield Advisor Group around the opposite idea: bring them to the same table, so every piece of your plan actually fits.
Financial advisor
Income and investments
Building dependable retirement income and positioning assets around protection.
CPA
Tax strategy
Keeping more of what you have saved through smarter withdrawal timing.
Insurance
Protection and income
Guarding against long-term care, longevity, and market shocks that plans often ignore.
Attorney
Estate and legacy
Documenting your wishes so your family is not left with a mess.
Advisor, CPA, insurance, attorney. One plan that fits together.
The pieces that matter most in the years around retirement, handled together rather than in isolation.
Retirement income planning
A strategy designed so your savings last as long as you do, however long that is.
Read moreInvestment and portfolio management
Portfolios aligned with your retirement goals and your real tolerance for risk.
Read moreSocial Security optimization
When to claim, and how to coordinate it with everything else in the plan.
Read moreTax-efficient retirement planning
Reducing lifetime taxes through Roth conversions and withdrawal sequencing.
Read more401(k) and IRA planning
Optimizing contributions, rollovers, and withdrawals across your accounts.
Read moreMedicare and healthcare planning
Understanding your Medicare options and preparing for the cost of care.
Read moreEstate and legacy coordination
Working with estate attorneys so your wealth transfers according to your wishes.
Read moreLong-term care and insurance
Evaluating long-term care, life insurance, and annuity needs honestly.
Read moreCash flow and budget planning
A sustainable spending plan built from your projected income and expenses.
Read moreComprehensive financial planning
A holistic plan covering retirement readiness, goals, risk, and the decisions in between.
Read more
The Preservation Blueprint™
01
Everything you own, on one page.
02
We try to break your retirement on purpose.
03
The plan itself, in plain English.
04
The part most plans never reach.
05
A plan is a relationship, not a document.
Most people arrive having been sold to before. These are clients describing what it was actually like.
We had three accounts in three places and no idea if any of it added up. Sean put it on one page in the first meeting. That page is still on our refrigerator.
Marlene R.
Client since 2018. Former school administrator, Jupiter.
I came in expecting a sales pitch for an annuity. I got a two-hour conversation about my wife's survivor benefit, and no product at all for four months.
Gerald P.
Client since 2016. Retired tool and die maker.
The Roth conversions alone changed what our kids will inherit. Nobody in twenty years had ever mentioned the ten-year rule to us.
Dennis and Kay W.
Clients since 2019. Former small business owners.
My husband handled all of it. When he died I could not have told you where the money was. Sean found it, listed it, and told me which decisions could wait. Most of them could.
Charlotte B.
Client since 2021. Widowed 2021, North Palm Beach.
I asked him straight out how he gets paid. He answered in one sentence without looking at his shoes. That is why I stayed.
Ray T.
Client since 2015. Retired plant supervisor, Lubrizol.
Testimonials were provided by current clients and are used with written permission. No compensation of any kind was provided. A testimonial is not a guarantee of any future result.
Top Financial Advisers, Northeast Ohio
Crain's Cleveland Business
2021 - 2025
Five Star Wealth Manager
Five Star Professional
2022 - 2025
Best of Stark County, Financial Planning
The Canton Repository
2023, 2025
Awards and ratings are not indicative of future performance and do not constitute an endorsement. Placement was obtained through a combination of qualification and paid participation, and the criteria for each award are available on request.
As seen on


Coverage was syndicated across affiliate news sites. Mention by a news outlet is not an endorsement, a recommendation, or an indication of investment results. Read the full disclosures.
Penfield Advisor Group press coverage: ABC, CBS, NBC, The Associated Press, Barchart, International Business Times, Sports Illustrated.
Questions people ask
These are the real questions people bring to a first conversation about retirement, with honest starting-point answers. Yours may differ, and that is what the meeting is for.
It is the question behind almost every other one. The honest answer depends less on a magic number and more on your spending, your other income, how long you might live, and how your money is positioned. A good plan replaces the guessing with a clear picture, stress-tested against bad markets and a long life, so you can see it rather than hope for it.
There is no single right age. It depends on your health, your other income, your spouse, and your tax picture. Waiting increases your monthly benefit, but claiming earlier makes sense in some situations. Because a married couple can have dozens of claiming combinations, and the lifetime difference can reach six figures, it is worth coordinating with the rest of your plan rather than deciding in a vacuum.
The goal is to convert accounts built for growth into a paycheck that lasts. That usually means deciding which accounts to draw from and in what order, how much to keep in accessible reserves, and how much of your essential expenses to cover with dependable, protected income. The right mix is personal. It should reflect your comfort with risk, not a rule of thumb.
Taxes are one of the largest and most controllable costs in retirement. The order you tap accounts, the timing of Roth conversions, and planning around required minimum distributions can meaningfully change how long your money lasts and what your heirs inherit. With a CPA on the team, this gets coordinated rather than handled after the fact.
That is exactly what a preservation-first plan is built for. The idea is to reduce how much of your near-term income depends on market timing, so a downturn does not force you to sell at the worst moment or change your life. We plan for bad years on purpose, because they will happen.
Fee-based, disclosed in writing, and never a surprise. Ongoing planning and investment management are charged as an annual percentage of the assets we manage for you, billed quarterly, starting at 1.00% and stepping down as the balance grows. Insurance products, where they are genuinely the right answer, pay a commission from the issuing company. You are told which is which, in writing, before anything is implemented. The conflict is worth naming plainly rather than burying: a commission is paid by the company whose product is sold, which gives any adviser a reason to prefer the product that pays. That is exactly why nothing is recommended in a first meeting, why the alternatives are shown to you, and why you should ask this question of every adviser you meet, including this one.
$250,000 in investable assets, applied with judgement rather than as a wall. Someone two years from a large rollover is not turned away over it. If you are below it, we will tell you honestly whether we are the right fit, and point you somewhere better if we are not. That is a more useful answer than a meeting neither of us should be in.
No. Sean meets clients in person around Palm Beach, Florida and by secure video across the country, so you can plan from the comfort of home.
Often, yes, especially as you approach retirement, when the strategy should shift from growing your money to protecting it. A review is complimentary and there is no obligation to change a thing.
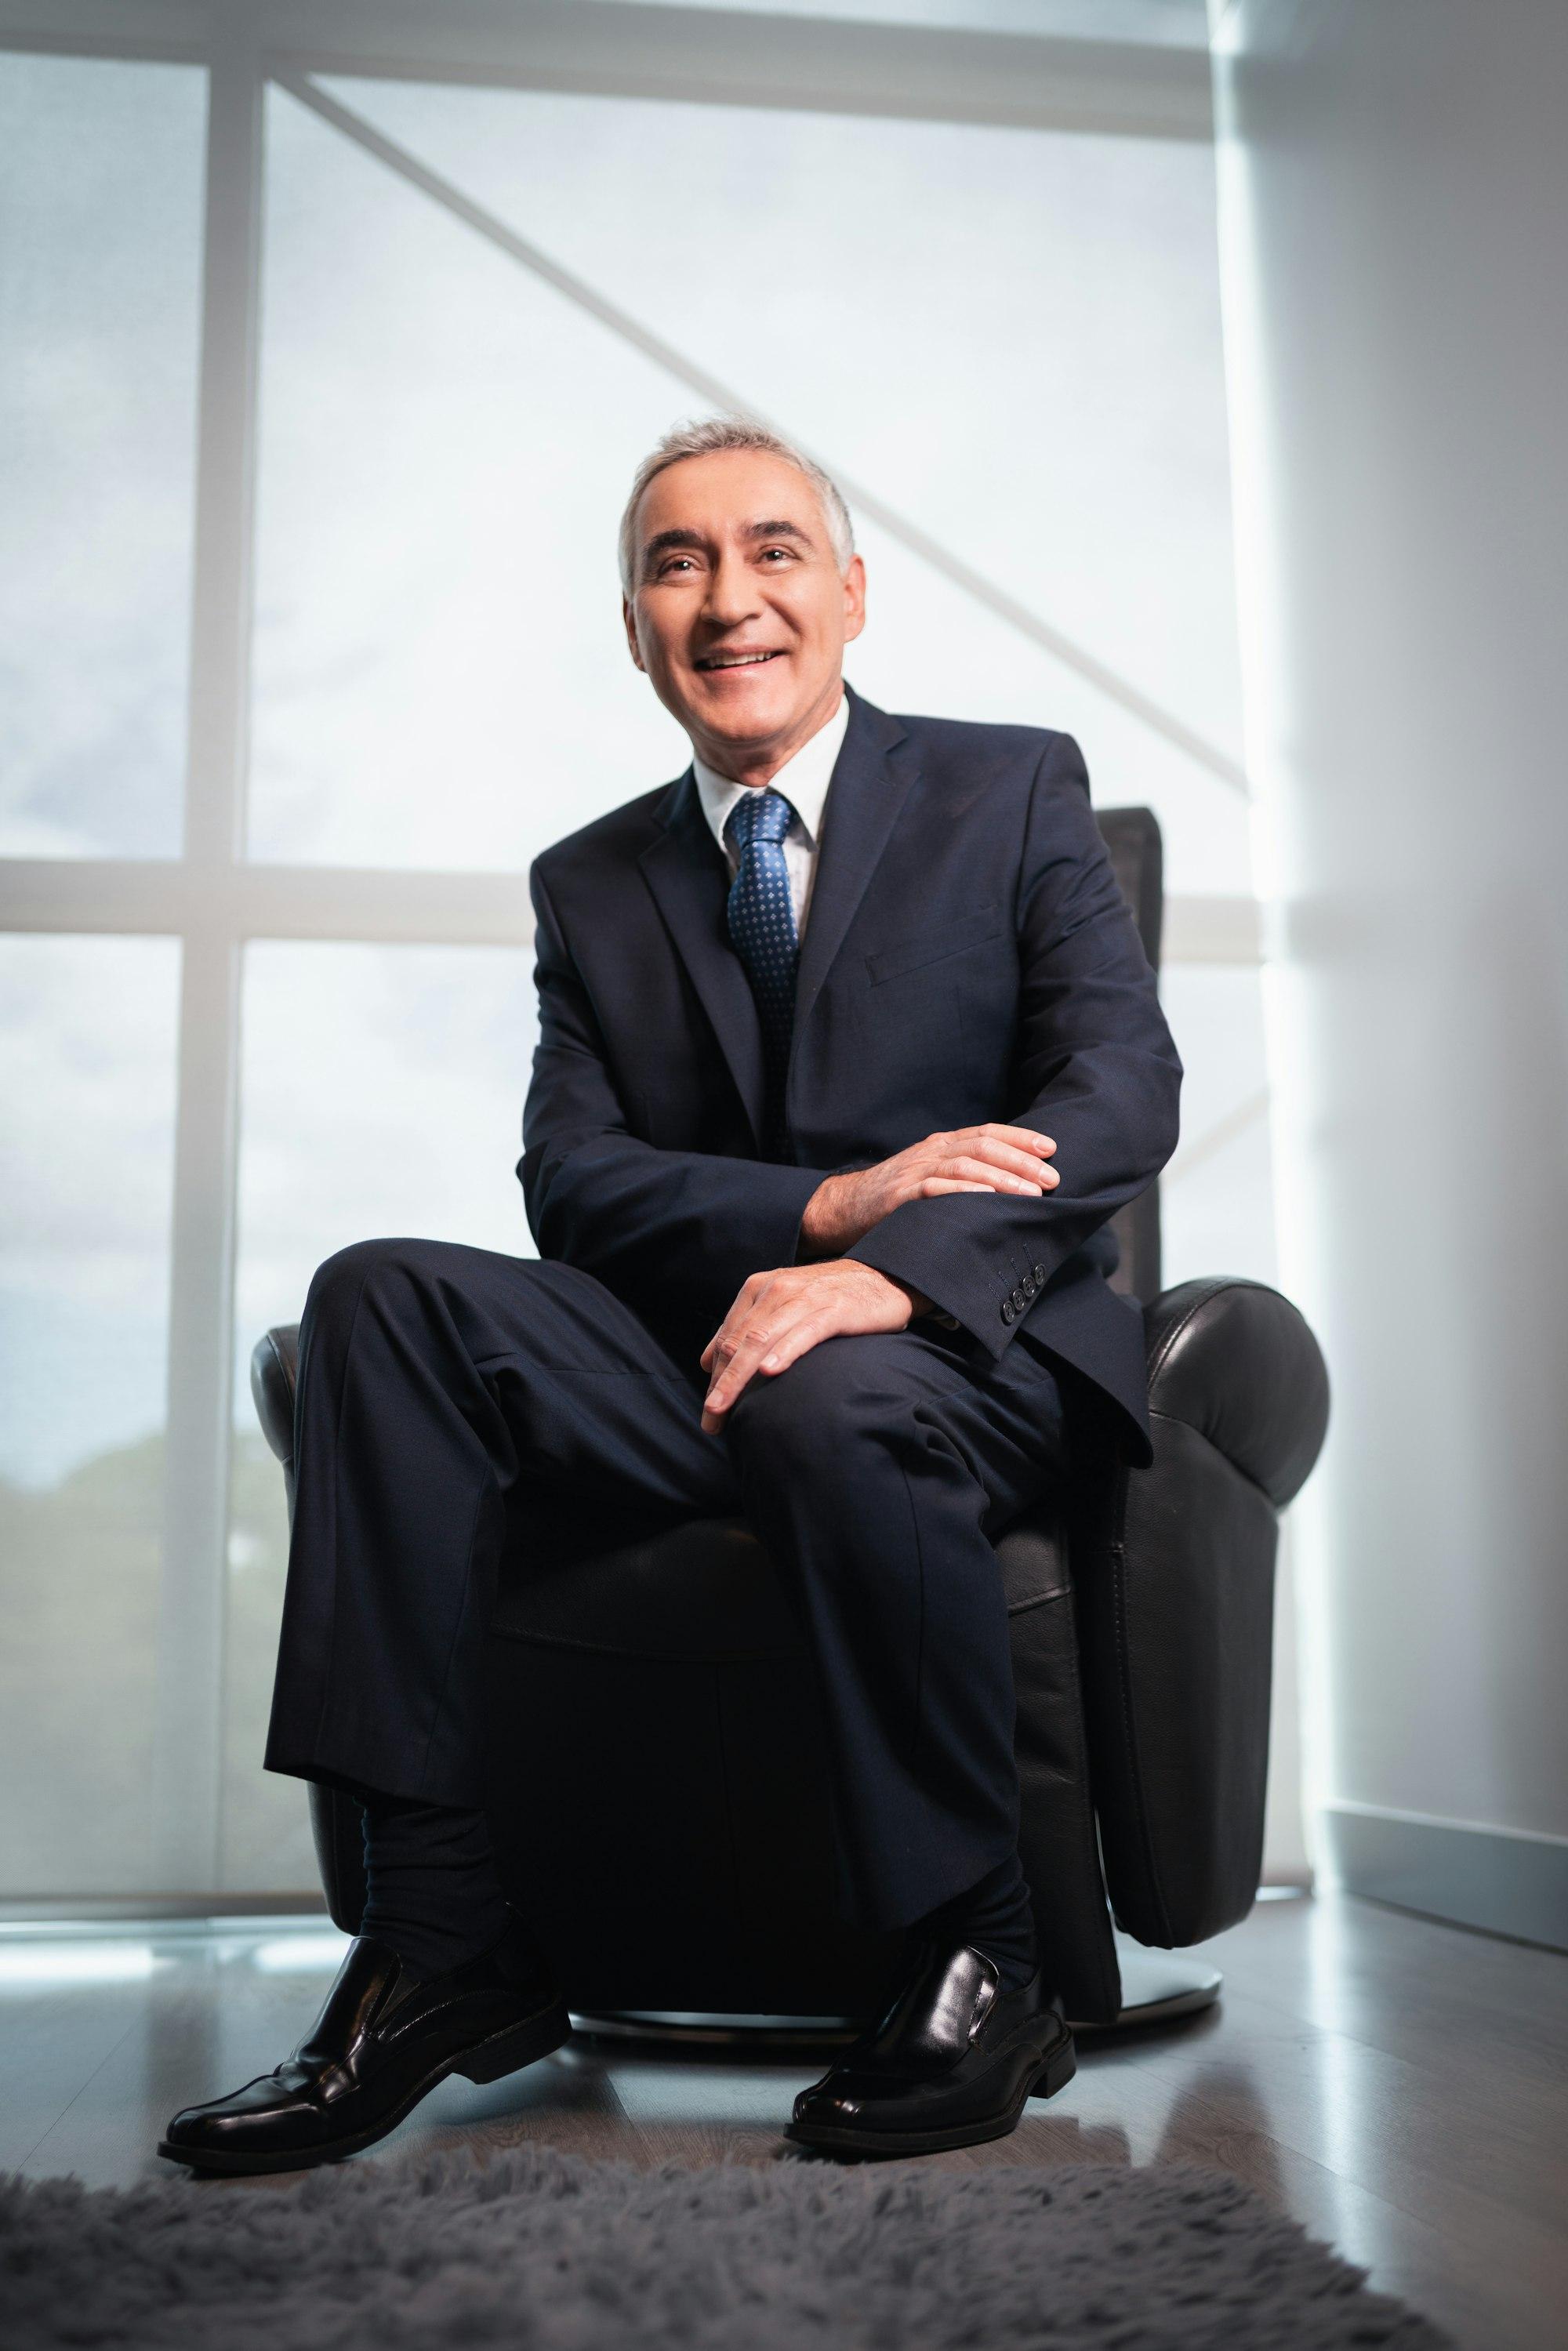
Sean Conrad founded Penfield Advisor Group, a Palm Beach, Florida firm built around retirement and estate preservation. He helps families navigate the shift from earning a living to living off what they have earned.
He started the firm because the pieces that decide a retirement, income, taxes, insurance, and estate, are almost always handled in silos by people who never speak. The team he assembled, advisors, CPAs, insurance specialists, and attorneys, works from one plan instead.
Sean Conrad
Founder, Penfield Advisor Group
No cost. No obligation. Just a clear look at where you stand and what a preservation-first plan could do for you.